
Crossing the Chasm: who moves first?
What will trigger the next wave of digital asset banking in Switzerland? Our CV Summit workshop poll: a large bank moving first, and clients starting to ask. Without a clear path to 24/7 on-chain operations and a digital Swiss franc, the followers have little reason to migrate.

At the CV Summit on 30 September 2026, Markus Perdrizat (ACK) and Matthias Staubli (PwC) hosted the workshop "Crossing the Chasm – What Will Trigger the Next Wave of Digital Asset Banking?" Starting from the Blockchain Pulse Survey 2026, we asked what it will take for the followers, the roughly 80% of Swiss banks still waiting for a business case, to join the pioneers.
The discussion gave a clear answer on why they are waiting. Client demand is too weak, and without it there is no strategic imperative to move. Measured against that demand, the change required across IT systems, compliance and regulation is prohibitive: almost half of the surveyed institutions run digital assets with one FTE or less, and 46% name compliance and regulatory requirements as a hurdle. Most banks also rely on service providers for IT and, to a large degree, for business process outsourcing, and participants noted that none of the main banking outsourcers has a mature digital asset offering yet.
We also looked at where the journey leads: "Banking 3.0", in which tokenized real-world assets trade and settle on-chain around the clock. That destination is still distant. At around USD 60bn worldwide, tokenized real-world assets remain tiny and are not driving business demand. One reason specific to Switzerland is that the settlement rails are incomplete: there is no solid Swiss franc stablecoin, and no broadly available digital franc issued by the SNB.
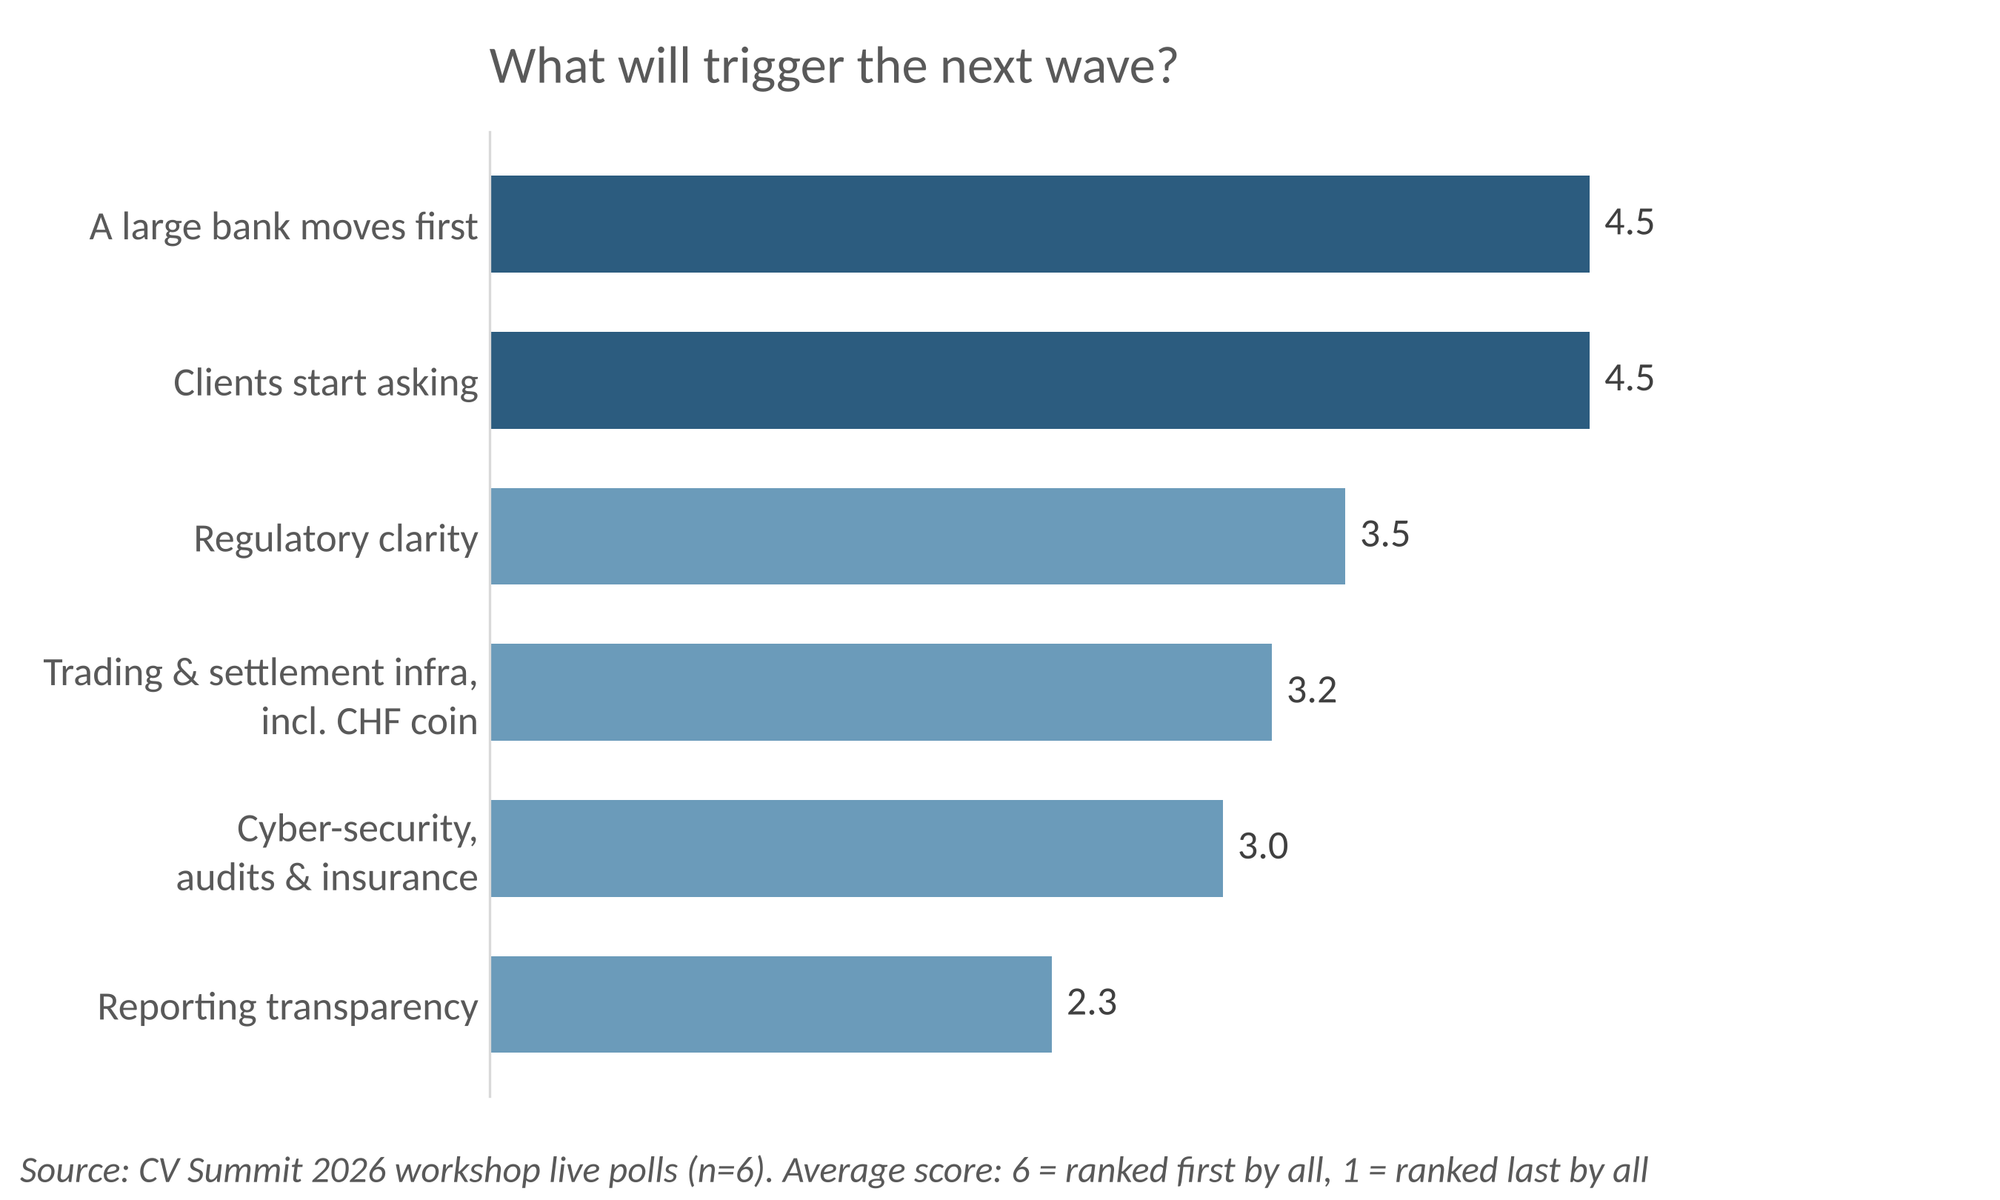
The live poll points the same way. Asked to rank six possible triggers, participants put two level at the top: a large bank moving first, and clients starting to ask. Five of six had a large bank in their top two. Regulatory clarity landed in the middle, and settlement infrastructure including a CHF coin ranked fourth. Reporting transparency came last.
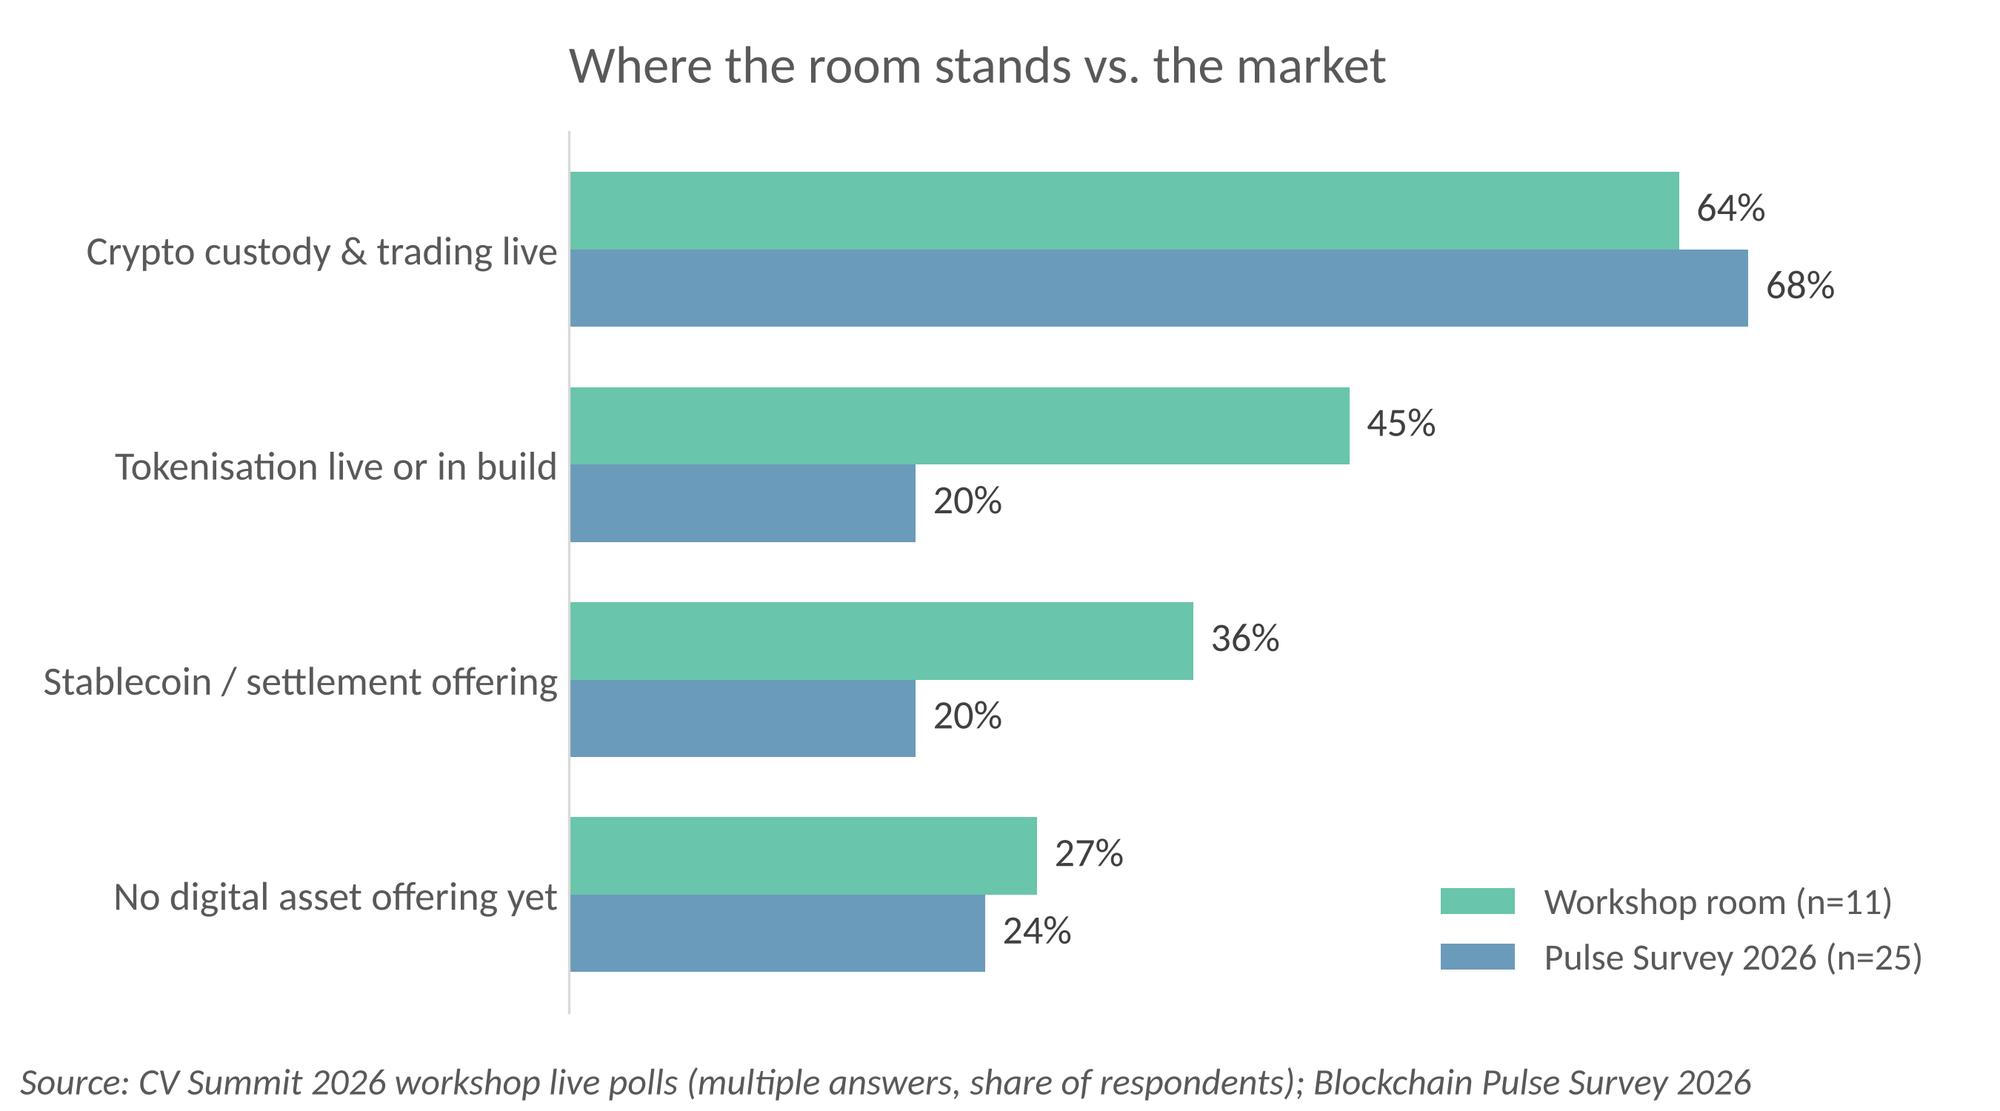
The room itself was ahead of the market. The share with a live crypto offering matched the survey (64% vs 68%), but tokenization and stablecoin or settlement offerings were roughly twice as common among participants as among the surveyed institutions.
Even so, a live offering does not yet put digital assets on the board agenda. Three of the eight institutions with a live offering say the topic is not a board priority today, two of them not before 2029.

In short, the market itself is the strongest driver. Clients asking would create the demand, and a large bank moving first would make digital assets a strategic imperative. Both need something to build on. As long as there is no clear path to 24/7 on-chain operations for tokenized real-world assets, with a digital Swiss franc to settle in and the major banking service providers on board, the followers have little reason to start migrating now.
Live polls with 11 and 6 participants; results are indicative.
Download the full report
Die Blockchain Pulsmesser Studie 2025 ist auch auf Deutsch verfügbar: